If you’re similar to many individuals, you might wonder, “Will my super account hold enough for a comfortable retirement?” or “What’s the ideal amount of super to aim for at my current age?”

There are primarily two methods for contributing to your superannuation: concessional and non-concessional. Concessional contributions involve allocating pre-tax dollars to your superannuation account, while non-concessional contributions are made with after-tax funds.
Concessional Contributions (CC)

Concessional Contributions include:

  • personal contributions for which you claim a tax deduction,
  • salary sacrifice contributions to super and
  • employer Super Guarantee contributions.

The CC cap is indexed to average weekly ordinary time earnings (AWOTE). The new indexed amount is generally available each February.

Income Year Your Concessional Contribution Annual Cap
2026-2027 $32,500
2024-2025 to 2025-2026 $30,000
2021-2022 to 2023-2024 $27,500
2017-2018 to 2020-2021 $25,000

If you’re 67 to 74 years old, you will be required to meet the work test or work test exemption in order to claim a deduction for a personal superannuation contribution. No contributions can be made for this cap when you are 75 or over.

To claim the contribution as a deduction in your tax return, you must lodge a deduction notice (using the approved form) with the fund before the earlier of:

  • the day they lodge their tax return for the year in which the contribution was made or
  • the end of the financial year after the financial year in which the contribution was made.

If you have an SMSF, we will prepare these documents when preparing the superfund financials and returns.

CCs attract contributions tax of, generally, 15% payable by the Super Fund.

Non-Concessional Contributions (NCC)

Cap as per the below provided, your total superannuation balance (TSB) was less than $2.1 million as of 30 June 2026.

Income Year Your Non-Concessional Contribution Annual Cap
2026-2027 $130,000
2024-2025 to 2025-2026 $120,000
2021-2022 to 2023-2024 $110,000
2017-2018 to 2020-2021 $100,000

The most tax-effective component within superannuation is NCCs, which are not taxed upon withdrawal. As a result, in general, you are able to take all of your NCCs as a lump sum and pay no tax, making NCCs an important super contribution consideration.

You can contribute to this cap without any restrictions as long as you are under 75.

Bring Forward Rule:

If your TSB is under the balance set out below, you can bring forward up to 2 future years caps into this year.

TSB (as of the end of the previous FY) NCC cap
Less than $1.84 million 3 x NCC annual cap
$1.84 million to less than $1.97 million 2 x NCC annual cap
$1.97 million to less than $2.1 million 1x annual cap (Bring forward not available)
$2.1 million or more Nil NCC cap

If the bring-forward cap is triggered but not used in full in the 2025-26 year, the remaining cap can only be used in the 2026-27 year when the individual’s TSB is less than $2.1 million as of 30 June 2026.

Carry Forward Concessional Contribution Cap

From 1 July 2018, you can make ‘carry-forward’ concessional super contributions if your total superannuation balance is less than $500,000 at 30 June of the previous financial year.

You can access your unused concessional contributions caps on a rolling basis for five years. Amounts carried forward that have not been used after five years will expire.

The first year you could access unused concessional contributions was the 2019–20 financial year. For the 2026–27 year, unused caps from 2021–22 to 2025–26 can be used. Any unused cap from 2021–22 expires after 30 June 2027.

In this example for the 2026/27 tax year:

  • You earn $100,000 per year
  • Your super balance was $280,000 at 30 June 2026
  • You have not made any extra contributions to super since FY 2021-22 (only employer Super Guarantee contributions)

Your Carry Forward Concessional Contribution Cap is the last five years of unused caps, totalling $87,500.

Income Year Your Concessional Contribution Cap Your Contributions Unused Concessional Contribution Cap
2025-2026 $30,000 $12,000 $18,000
2024-2025 $30,000 $11,500 $18,500
2023-2024 $27,500 $11,000 $16,500
2022-2023 $27,500 $10,500 $17,000
2021-2022 $27,500 $10,000 $17,500
Total $87,500

This means your total concessional contributions in 2026–27 could be up to $120,000 ($32,500 cap plus $87,500 carried forward). Your employer’s Super Guarantee contributions for 2026–27 count towards this amount.

Spouse Contribution Tax Offset

If you have a spouse with assessable income, reportable fringe benefits and reportable employer contributions (super salary sacrifice contributions) of less than $40,000 you could consider making a non-concessional contribution to your spouse’s super fund.

The offset is calculated as 18 per cent of the contribution, up to a maximum of $540 where the spouse’s income is below $37,000.
A reduced offset may apply where the spouse’s income is between $37,000 and $40,000.

Therefore, if you contribute $3,000 to your spouse’s super, you will get a $540 tax offset (decrease to your tax debt) in your personal tax return.

Please note – No offset is available where:

  • the spouse’s income is above the $40,000 threshold;
  • the spouse has excess non-concessional contributions; or
  • the spouse’s Total Superannuation Balance exceeds $2.1 million as at 30 June 2026.
Government Co Contribution

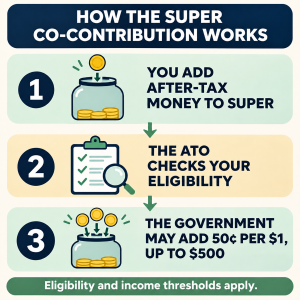
Is your assessable income, reportable fringe benefits and reportable employer super contribution (super salary sacrifice contributions) minus deductions from carrying on a business less than $64,293?

Consider making a non-concessional contribution of up to $1,000 to super.
The maximum co-contribution is 50 per cent of the contribution, up to a maximum of $500 for income below $49,293.

If your total income is equal to or less than the lower threshold (currently $49,293) and you make personal non-concessional contributions of $1,000 to your super account, you will receive the maximum co-contribution of $500.

You won’t receive any co-contribution if your income is equal to or greater than the higher threshold (currently $64,293).

If your total income is between the two thresholds, your maximum entitlement will reduce progressively as your income rises. If your co-contribution is less than $20, the government will pay the minimum amount of $20.

Please note:
The co-contribution will not be available where the client has excess non-concessional contributions or their TSB exceeds $2.1 million as of 30 June 2026.

Eligibility requires that a minimum of 10% of assessed income relates to income from employment or carrying on a business.

Spouse Contribution Splitting

You can split up to 85 per cent of your concessional contributions made during a financial year (up to the concessional contribution cap) with your spouse, provided your spouse is not aged 65 or over, or reached their preservation age and retired.

This includes concessional contributions which utilises the client’s carry-forward unused concessional contribution cap. For example, someone who contributed $42,500 in 2026-27 (being their 2026-27 cap of $32,500 plus $10,000 of their carry forward cap) would be able to split up to $36,125 (i.e. 85 per cent of $42,500) to their spouse.

The application to split contributions must generally be made before the end of the financial year immediately after the financial year in which the contribution was made.
This means that the application to split contributions for 2025-26 must be made by 30 June 2027.


Please note:
The concessional contributions will still count towards the cap of the spouse who made the contributions and not the cap of the spouse who receives the split contributions.

Therefore, it cannot remove any excess concessional contributions tax that you may have to pay.

Downsizer contribution

The Downsizer Contribution allows eligible individuals to contribute up to $300,000 from the proceeds of the sale of a qualifying dwelling into super where specific requirements are met.

See more on this here:
https://www.austasiagroup.com/news/investments/boost-your-super-retirement-savings-downsizer-contribution/